How Liability Insurance Fault Rules Affect Your Injury Claim
Fault rules can make or break your injury claim. This guide explains at-fault vs. no-fault systems and comparative negligence. Call (833)-670-8160 for a free case review.
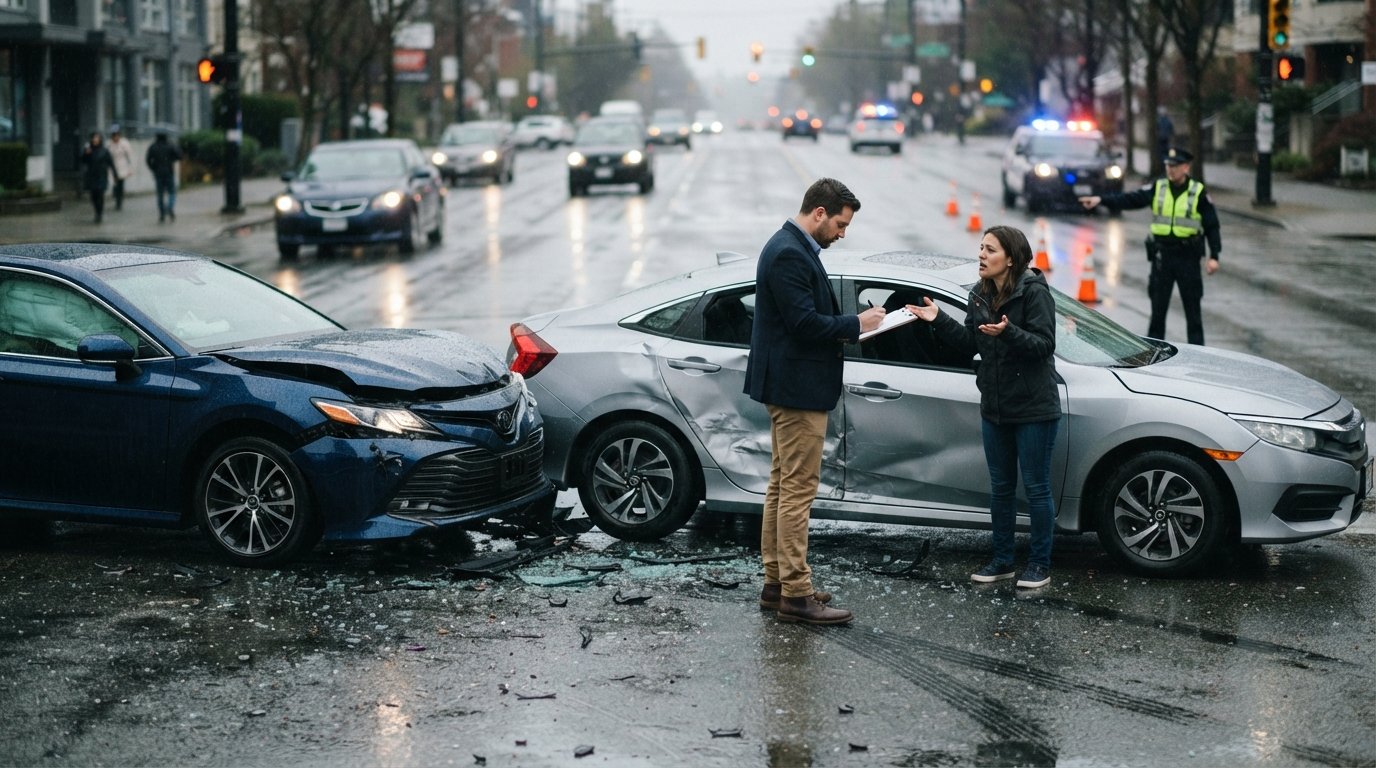
Your injury claim's value, timeline, and even your ability to recover anything at all can hinge on a single legal concept: fault. When you file a claim after a crash, the insurance adjuster does not simply write a check based on your medical bills. Instead, they apply a set of liability rules that determine who was responsible, how much responsibility each party bears, and whether your own actions reduce your payout. Understanding these rules before you negotiate can mean the difference between a fair settlement and a lowball offer that leaves you covering thousands in out-of-pocket costs.
This guide breaks down how fault rules work across different state systems, how insurers investigate liability, and what happens when multiple parties share blame. It also explains practical steps you can take to protect your recovery when the fault picture is complicated. The information here is educational only and is not legal advice; for guidance on your specific situation, a free case review with a licensed attorney is the safest next step.
At-Fault Versus No-Fault Systems: Two Different Roads to Recovery
The first question that shapes any injury claim is which fault system your state uses. In traditional at-fault states, the person who caused the accident (or their insurer) pays for the harm they caused. You file a claim against the other driver's liability policy, and you must prove that driver was negligent to recover. This system gives you the right to sue for pain and suffering, lost wages, and other non-economic damages, but it also means you may wait longer for payment while fault is disputed.
No-fault states take a different approach. After a crash, each driver turns to their own personal injury protection (PIP) coverage for medical bills and lost wages, regardless of who caused the collision. This speeds up payment for basic expenses, but it also restricts your ability to sue the other driver. In most no-fault states, you can only file a lawsuit if your injuries meet a serious injury threshold, such as significant disfigurement, a fracture, or permanent impairment. If you live in a no-fault state and your injuries are moderate, your claim may be limited to your PIP benefits, which often cap out well below your actual losses.
Understanding which system applies to you is critical because it determines the entire claims process. In an at-fault state, you will spend time gathering evidence to prove the other driver's negligence. In a no-fault state, you may need to prove that your injuries cross the legal threshold before you can pursue a liability claim at all. Some states use a hybrid model, allowing drivers to choose between no-fault and traditional coverage, which adds another layer of complexity.
Comparative and Contributory Negligence: When Your Own Actions Reduce Your Award
Even in at-fault states, fault is rarely a simple binary. Most crashes involve some degree of shared responsibility, and the legal doctrine of negligence governs how that shared fault affects your recovery. There are three main approaches: pure comparative negligence, modified comparative negligence, and contributory negligence.
Under pure comparative negligence, you can recover damages even if you were 99 percent at fault, but your award is reduced by your percentage of responsibility. If a jury finds you 30 percent at fault for a crash and your total damages are $100,000, you receive $70,000. Modified comparative negligence works similarly, but it includes a threshold, usually 50 or 51 percent. If you are found more at fault than the threshold, you recover nothing. For example, in a 51 percent bar state, being 50 percent at fault still allows recovery, but being 51 percent at fault eliminates it entirely.
Contributory negligence is the harshest rule. In the few states that still use it, any fault on your part, even one percent, can bar you from recovering anything from the other party. This rule has been criticized as unfair and has been abandoned by most jurisdictions, but if you live in one of the remaining contributory negligence states, even a minor mistake like failing to use a turn signal could wipe out your claim.
These rules matter because insurance adjusters will aggressively assign fault to you if it reduces their payout. If you admit to checking your phone before a crash, an adjuster might argue you were distracted and assign you partial fault, reducing your settlement by 20 or 30 percent. That is why you should never give a recorded statement to an insurer without understanding how your words can be used to shift blame.
How Insurers Investigate Fault After an Accident
Insurance companies do not take your word for what happened. They conduct their own investigation to determine fault, and the evidence they gather directly shapes your claim. The adjuster will typically review the police report, which often includes an officer's opinion on fault and citations issued at the scene. However, police reports are not always conclusive, and adjusters may dispute an officer's conclusions if the physical evidence suggests otherwise.
Insurers also examine scene evidence, including photographs of vehicle damage, skid marks, and road conditions. They may hire accident reconstruction experts to calculate speeds and impact angles. Witness statements are another key piece of the puzzle, and adjusters will contact witnesses directly to get their version of events. If witness accounts conflict with yours, the insurer may use that inconsistency to argue you are partially or fully at fault.
Your own statements and social media activity can also be used against you. If you post about your injuries or the accident on social media, the insurer may monitor those posts to find inconsistencies or evidence that you were distracted or careless. For this reason, it is wise to avoid discussing your case online and to consult an attorney before giving any statements to the other driver's insurer. If you are researching how fault rules apply in specific states, resources like this guide on Wyoming car accident fault and liability insurance rules can illustrate how state-specific standards work in practice.
When Multiple Parties Share Fault for the Same Injury
Multi-vehicle crashes and accidents involving pedestrians or cyclists often involve several parties who share responsibility. In these cases, fault rules become even more important because each party's insurer will try to minimize its own share of liability. Some states follow joint and several liability, meaning any defendant who is found even partially at fault can be held responsible for the full judgment if other defendants cannot pay. Other states follow several liability, where each defendant pays only their proportionate share.
If you are injured in a multi-party accident, the claims process can become a web of cross-claims and counterclaims. Each insurer may point fingers at the others, and your own percentage of fault may be disputed by multiple parties. An experienced attorney can help you sort through the evidence and ensure that all responsible parties are held accountable. Without legal representation, you risk settling with one insurer for a fraction of your damages while unknowingly releasing other liable parties from future claims.
In some cases, the fault of a non-party can also affect your claim. For example, if a mechanic's negligent repair contributed to a crash, the at-fault driver's insurer may argue that the mechanic shares responsibility. This can complicate your claim and may require adding the mechanic as a defendant. The more parties involved, the more important it becomes to have a clear strategy for proving fault and maximizing your recovery.
Why Fault Rules Differ by State and How to Confirm Your State's Standard
Fault rules are set by state law, and they vary dramatically from one jurisdiction to the next. The differences go beyond just at-fault versus no-fault: states also differ on comparative negligence thresholds, serious injury thresholds for lawsuits, and rules for uninsured motorist claims. A rule that applies in California may be completely different in Texas or Florida.
To confirm your state's standard, start by researching your state's department of insurance or motor vehicle agency website. These resources often explain the basic fault system and coverage requirements. You can also consult a local personal injury attorney, who will know the specific rules and how courts in your area apply them. If you are considering a free case review, services like AutoInjuryAccident can connect you with participating attorneys who handle car crash and truck wreck claims nationwide, though fault rules and deadlines still vary by state.
Do not assume that because you were not ticketed at the scene, you are automatically fault-free. Insurance adjusters can assign fault based on their own investigation, and their conclusions may differ from the police report. Similarly, do not assume that because the other driver was ticketed, they are 100 percent at fault. The ticketed driver may argue that you contributed to the crash, and the insurer may reduce your award accordingly.
Understanding how liability insurance fault rules affect your injury claim is not just an academic exercise. These rules determine whether you can recover, how much you can recover, and how long it will take. If you are uncertain about your state's rules or how they apply to your case, a consultation with a qualified attorney is the most reliable way to protect your rights. AttorneyLawsuit.com is an informational resource that can help you understand your options and request a free, confidential case review with a participating attorney; it is not a law firm and does not provide legal advice.
Finally, keep in mind that insurance companies are businesses, and their adjusters are trained to minimize payouts. They know the fault rules in their state, and they will use them to their advantage. By educating yourself on these rules and seeking legal guidance when needed, you can level the playing field and pursue the compensation you deserve.