Uninsured Motorist Coverage After a Hit and Run Accident
Uninsured motorist coverage after a hit and run accident can be your safety net. Call (833)-670-8160 to discuss your options with a professional.
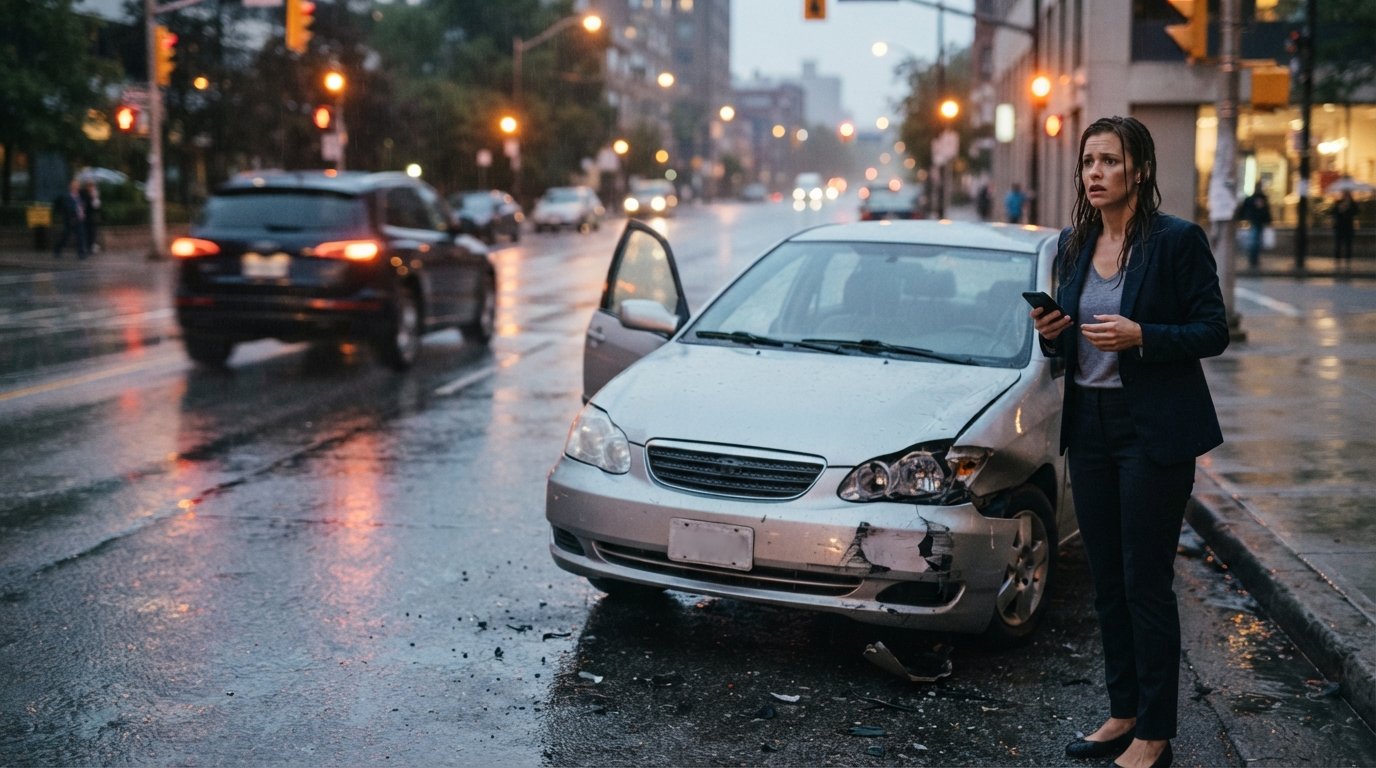
A hit and run accident leaves you injured, stranded, and facing a driver who vanished before you could even exchange information. The immediate question is who pays for your medical bills, lost wages, and vehicle damage when the at-fault driver cannot be identified. The answer often lies in your own auto insurance policy, specifically uninsured motorist coverage after a hit and run accident. This coverage exists precisely for situations where the responsible party is unknown or lacks insurance, but accessing those benefits is rarely automatic. Insurers scrutinize these claims closely, and policyholders frequently encounter denials or lowball offers. Understanding how UM coverage functions, what steps to take immediately after the collision, and how to challenge an unfair denial can mean the difference between a paid claim and financial hardship.
How Uninsured and Underinsured Motorist Coverage Works on Your Own Policy
Uninsured motorist (UM) coverage is a component of your auto insurance that steps in when you are injured by a driver who has no liability insurance or who cannot be identified, such as in a hit and run. Underinsured motorist (UIM) coverage applies when the at-fault driver has insurance, but the limits are too low to cover your damages. Both types of coverage operate on your own policy, which means you file a claim with your insurer, not the fleeing driver's. The insurer then pays up to your policy limits for medical expenses, lost income, pain and suffering, and other damages, depending on your state's rules.
Many drivers assume their liability coverage protects them, but liability insurance covers damage to others, not yourself. UM and UIM coverage are typically optional add-ons in most states, though some jurisdictions require them. If you declined UM coverage at purchase, your options after a hit and run may be severely limited. That is why reviewing your declarations page immediately after an accident is critical. The page lists your coverage types and limits, including whether UM and UIM are present and what they cover.
It is also important to distinguish between UM coverage for bodily injury and UM coverage for property damage. Some policies include both, while others separate them. After a hit and run, your collision coverage may handle vehicle repairs (minus your deductible), but UM coverage addresses personal injuries. Stacking, which combines limits across multiple vehicles or policies, can increase available compensation in some states, but rules vary widely. A knowledgeable attorney can help you interpret your policy and identify all potential sources of recovery.
What to Do Immediately After a Hit and Run to Preserve a UM Claim
The moments after a hit and run are chaotic, but the actions you take in the first hours and days can significantly affect your ability to recover under uninsured motorist coverage. Your first priority is safety: move to a secure location, call 911, and seek medical attention for any injuries. Even if you feel fine, adrenaline can mask pain, and a medical record linking your injuries to the accident is essential for a UM claim. Once immediate needs are addressed, focus on gathering evidence and documenting the scene.
Because the at-fault driver fled, you must rely on other sources to prove the accident occurred and that the other driver was at fault. Witness statements, surveillance footage, and police reports become your primary tools. Notify the police and request a copy of the report, which will document the hit and run and support your claim. If any witnesses stopped, collect their contact information and ask what they saw. Photograph the damage to your vehicle, the surrounding area, and any visible injuries. These details help establish that a phantom driver caused the crash, a requirement for UM claims in many policies.
Next, report the accident to your own insurance company promptly. Most policies require timely notice, and delays can give the insurer grounds to deny coverage. When speaking with the claims adjuster, stick to the facts: describe the accident, the other driver's actions, and your injuries. Avoid speculating about fault or downplaying your symptoms. Keep a file with all correspondence, medical records, repair estimates, and witness statements. This organized evidence trail strengthens your position if the insurer disputes the claim.
- Call 911 and request a police report that documents the hit and run.
- Seek medical attention and keep all treatment records, even for minor symptoms.
- Collect witness names, phone numbers, and any photos or video of the scene.
- Notify your insurer within the timeframe stated in your policy.
- Avoid giving a recorded statement without understanding how it may be used.
Following these steps creates a clear record that the accident happened, that the other driver fled, and that your injuries are real. Without this foundation, even valid UM claims can falter. If you are unsure about any step, a free case review through a service like AutoInjuryAccident.com can connect you with a participating attorney who can guide you through the process. Remember that fault rules, insurance requirements, and deadlines vary by state, so localized advice is invaluable.
Why Insurers May Deny a UM Claim and How to Challenge a Denial
Insurance companies are businesses, and paying claims reduces their profits. When you file a UM claim after a hit and run, the insurer may look for reasons to deny or minimize payment. Common denial grounds include late reporting, lack of proof that an uninsured or hit-and-run driver caused the accident, disputes over the extent of your injuries, or allegations that you violated a policy condition. For example, if you waited weeks to report the accident, the insurer might argue it was prejudiced by the delay. Similarly, if you cannot provide a police report or witness evidence, the insurer may question whether a hit and run actually occurred.
Another frequent issue is the insurer's claim that your injuries pre-existed the accident or are not as severe as you claim. They may request an independent medical examination (IME) and use the results to reduce your payout. Some insurers also assert that you failed to cooperate or that your policy lapsed. To challenge a denial, you need to counter these arguments with evidence. Obtain a copy of your policy and review the conditions for UM coverage. Gather all documentation, including the police report, medical records, and correspondence with the insurer. Then, submit a written dispute that addresses each reason for denial and attaches supporting evidence.
If the insurer still refuses to pay, you may need to escalate. Many policies include an appraisal or arbitration clause for disputes over the amount of damages. In some states, you can file a complaint with the state insurance department. However, the most effective route is often to consult an attorney who handles insurance bad faith and UM claims. Attorneys can negotiate with the insurer, demand arbitration, or file a lawsuit. They understand the tactics insurers use and can hold them accountable. Keep in mind that deadlines for challenging a denial can be short, so act quickly.
When to Consult an Attorney About a UM Dispute
Not every UM claim requires legal representation, but certain red flags suggest you should seek professional help. If your insurer denies your claim outright, delays payment without justification, or offers an amount that seems far too low, an attorney can evaluate whether you are being treated unfairly. Similarly, if the accident involved serious injuries, significant lost wages, or a dispute over who was at fault, legal guidance can protect your rights. Attorneys can also help if you are unsure whether your policy includes UM coverage or if you face pressure to sign a release or give a recorded statement.
Consulting an attorney does not necessarily mean filing a lawsuit. Many lawyers offer free consultations and can often resolve disputes through negotiation or arbitration. They can explain your options, help you gather evidence, and communicate with the insurer on your behalf. If litigation becomes necessary, they can file a bad faith claim or a breach of contract lawsuit against your insurer. The cost of an attorney is often contingent on recovery, meaning you pay nothing upfront and only a percentage if you win. This arrangement makes legal help accessible even if you are struggling financially after the accident.
When choosing an attorney, look for experience with uninsured motorist claims and hit and run accidents in your state. Ask about their track record and whether they handle appeals or arbitration. If you are unsure where to start, resources like AutoInjuryAccident.com can help you request a free, confidential case review from participating attorneys. The site is not a law firm or lawyer referral service, but it connects injured people with legal professionals who advertise on the platform. Coverage is nationwide, and there is no obligation to hire.
Key Steps to Maximize Your Recovery Under UM Coverage
Successfully recovering under uninsured motorist coverage after a hit and run accident requires a proactive approach. Start by understanding your policy inside and out. Know your UM and UIM limits, whether stacking is allowed, and what conditions you must satisfy. Report the accident promptly and cooperate with your insurer, but avoid volunteering information that could be used against you. Document everything: medical visits, missed work, pain levels, and communications with the insurer. This evidence builds a compelling case for the full value of your claim.
Be cautious with early settlement offers. Insurers may rush to offer a quick check before you know the full extent of your injuries. Once you cash the check, you may waive your right to additional compensation. Have an attorney review any offer, especially if you are still treating or expect future medical costs. Also, be aware of statutes of limitations. Even UM claims have deadlines, and missing them can bar your recovery entirely. An attorney can ensure you file within the required timeframe.
Finally, do not overlook other potential sources of compensation. If the hit and run driver is later identified, you may be able to pursue a claim against them, though their lack of insurance may make collection difficult. Your health insurance, medical payments coverage (MedPay), or personal injury protection (PIP) may also cover some expenses. An attorney can coordinate these benefits to avoid gaps in coverage. By taking these steps, you can level the playing field with your insurer and pursue the compensation you deserve.
If you are facing a dispute over uninsured motorist coverage after a hit and run accident, do not navigate it alone. The legal system is complex, and insurers have teams of adjusters and lawyers working to minimize payouts. A qualified attorney can protect your interests and help you secure the recovery you need to move forward.