How to Document Lost Wages After a Car Accident
Learn how to document lost wages after a car accident to strengthen your claim and avoid a lowball offer. Call (833)-670-8160 for a free case review.
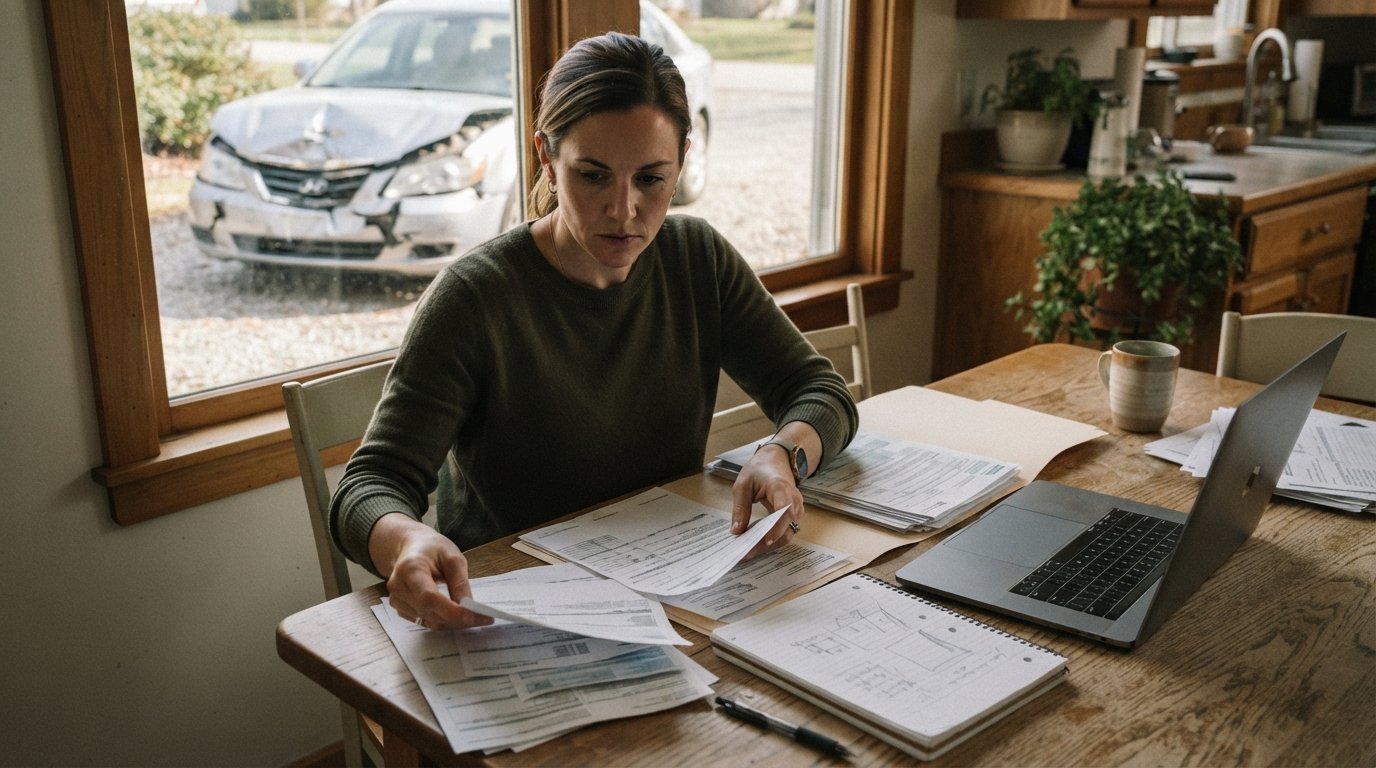
A car crash can upend your finances in ways that go far beyond the repair bill. When you cannot work because of your injuries, every missed paycheck adds pressure to an already stressful situation. Insurance adjusters know this, and they often challenge lost wage claims precisely because they expect injured people to lack organized proof. The good news is that documenting lost wages after a car accident is a skill anyone can learn, and a well-prepared file can shift the conversation from suspicion to settlement. This guide walks you through the records that matter, the mistakes that weaken claims, and the steps to take so your income loss is taken seriously.
Start With the Basics: Prove Your Income Before the Crash
Every lost wage claim begins with a simple question: what were you earning before the accident? Adjusters want to see a reliable baseline, and the strongest evidence comes from documents created before the crash, not after. Pay stubs, W-2s, and recent tax returns establish your normal earnings pattern. If you are a salaried employee, three to six months of pay stubs usually suffice. If your income fluctuates, gather twelve months or more so the adjuster can see the full picture.
An employer letter adds weight to these records. Ask your human resources department or supervisor for a letter on company letterhead that states your job title, your rate of pay, your normal schedule, and the dates you missed work because of the accident. The letter should also confirm any sick leave, vacation time, or paid time off you were forced to use. When you burn paid time off to cover accident-related absences, that is a real loss too, and many claimants overlook it.
A common mistake is submitting only the most recent pay stub. Adjusters may argue that a single check reflects an unusually good or bad week. Provide a series of stubs and, if possible, a year-to-date earnings statement. If you received bonuses, commissions, or overtime regularly, include documentation of those payments as well, because they count toward your average weekly wage in most states.
Documenting Self-Employment and Gig Economy Income
Self-employed workers face a higher burden of proof, but the task is manageable with discipline. Tax returns are the foundation: provide two or three years of returns along with profit and loss statements. If you maintain business bank accounts, highlight deposits that correspond to client payments. Invoices, signed contracts, and 1099 forms from clients all help establish a consistent income stream.
Gig workers, rideshare drivers, and independent contractors should pull earnings summaries from each platform they use. These summaries show weekly or monthly totals and are far more persuasive than screenshots of individual trips. Pair those summaries with bank statements showing the deposits. If you track mileage or expenses, keep that documentation separate, since lost wage claims focus on gross income, not net after expenses.
For self-employed claimants, a letter from a CPA or bookkeeper can be valuable. The letter should explain how your income is calculated and confirm that your earnings dropped after the accident. If you had to turn down contracts or delay projects because of your injuries, keep a written log of those lost opportunities. Even if you cannot prove the exact value of a missed project, the pattern of lost work supports your claim.
One practical tip: create a simple folder system, either physical or digital, with sections for pre-accident income, post-accident income, medical restrictions, and correspondence with employers or clients. A well-organized file signals credibility to an adjuster and makes your attorney's job easier. If you are unsure how to calculate a fair figure for your claim, a guide on the best way to calculate lost wages after an accident can help you put your numbers in context.
Proving Future Lost Earning Capacity
Lost wages are not limited to the paychecks you have already missed. If your injuries prevent you from returning to your previous job or from working at the same capacity, you may have a claim for lost earning capacity. This is a forward-looking claim, and it requires medical and vocational evidence rather than pay stubs alone.
Start with your treating physician. Ask for a written statement describing your work restrictions, your prognosis, and whether your limitations are temporary or permanent. If a specialist is involved, such as an orthopedic surgeon or neurologist, get a letter from that specialist too. The more specific the restrictions, the stronger the foundation for a future loss claim. For example, a letter stating that you cannot lift more than ten pounds or sit for more than thirty minutes is far more useful than a general note saying you are injured.
Vocational experts can bridge the gap between medical restrictions and lost income. A vocational rehabilitation specialist can assess your education, work history, and transferable skills, then explain how your injuries affect your ability to earn. In more complex cases, an economist may calculate the present value of future losses, accounting for raises, benefits, and retirement contributions. These experts cost money, but they are often essential when the future loss is substantial.
Keep in mind that insurance adjusters frequently dispute future loss claims because they are speculative by nature. Your documentation should be as concrete as possible. Gather performance reviews, promotion letters, and pay increase histories that show your career trajectory before the accident. If you were enrolled in a training program or had a job offer in hand, include that evidence. The goal is to show the adjuster what your earnings would likely have been, not just what they are today.
Common Mistakes That Weaken Lost Wage Claims
Even honest claimants can undermine their own claims through small oversights. Adjusters are trained to look for inconsistencies, and a single gap in your records can cast doubt on the entire claim. Avoiding these common mistakes will make your documentation more persuasive.
- Missing work without medical support. If you stayed home but your doctor did not formally restrict you from working, the adjuster may argue the absence was voluntary. Always get written work restrictions.
- Failing to document partial days and reduced hours. Many injured workers return part-time or with accommodations. Track those reduced hours carefully, because partial wage loss is still compensable.
- Using vague employer letters. A letter that says you missed work is weak. A letter that specifies dates, hours, and pay rates is strong.
- Overlooking paid time off. If you used sick leave or vacation days for accident recovery, document it. Those benefits have monetary value.
- Submitting disorganized records. A shoebox of receipts and stubs invites scrutiny. Create a clear summary sheet with totals and cross-references to supporting documents.
Another frequent error is waiting too long to gather records. Employers change payroll systems, supervisors leave, and digital records get archived. Start collecting documents as soon as possible after the accident, even if you are still recovering. A prompt request also signals to the adjuster that you are treating the claim seriously.
Finally, be careful with social media. Adjusters may review public posts, and a photo of you hiking or lifting something heavy can contradict your claimed restrictions. Privacy settings help, but the safest approach is to avoid posting about your activities until the claim is resolved.
Working With an Attorney and Using Consumer Resources
Documenting lost wages can be done on your own, but the stakes rise quickly when the income loss is significant or the insurance company disputes your claim. An experienced personal injury attorney can help you gather the right records, retain experts, and present your lost wage claim in the most persuasive light. Many attorneys offer free consultations and work on contingency, meaning you pay nothing upfront and the attorney's fee comes from the recovery.
If you are looking for a confidential case review, consumer matching services can connect you with participating attorneys who handle car accident claims. One option is AutoInjuryAccident.com, a consumer matching site that is not a law firm or lawyer referral service. It helps people injured in car crashes and truck wrecks request a free, confidential review from attorneys who advertise on the site. Coverage is nationwide, though fault rules, insurance requirements, and deadlines vary by state, so it is important to confirm local rules with a licensed attorney.
Before you sign anything, read the fee agreement carefully and ask how costs will be handled. Keep copies of all correspondence with the insurance company, including emails and letters. If an adjuster makes a verbal offer, follow up in writing to confirm the terms. A clear paper trail protects you if the claim later becomes a dispute.
Remember that this article is educational information, not legal advice. Every claim is different, and the right approach depends on your state's laws, your employment situation, and the severity of your injuries. A licensed attorney in your state can review your records and advise you on the best path forward.
Building a Complete Lost Wage File: A Step-by-Step Checklist
To keep the process manageable, break it into stages. First, gather pre-accident income records: pay stubs, tax returns, employer letters, and any documentation of bonuses or commissions. Second, document the accident and your medical restrictions with reports and physician letters. Third, track post-accident income and missed work, including partial days and paid time off used. Fourth, if future loss is a factor, consult medical and vocational experts and preserve evidence of your career trajectory. Fifth, organize everything into a clear file with a summary sheet that totals your losses and references each supporting document.
As you build the file, keep a daily log of symptoms, medical appointments, and work absences. A contemporaneous log is powerful evidence because it was created close in time to the events. Note the date, the hours missed, and the reason. If your employer provides a leave statement or attendance record, add it to the file. Small details add up, and adjusters respond well to claimants who can substantiate their claims with specific, consistent records.
When you are ready to present your claim, provide copies rather than originals, and keep a complete set for yourself. Send documents by a method that provides proof of delivery, such as certified mail or a tracked email. If the adjuster requests additional records, respond promptly and keep a log of what you sent and when. This professionalism can make the difference between a lowball offer and a fair settlement.
Documenting lost wages after a car accident is not glamorous work, but it is one of the most practical ways to protect your financial recovery. The effort you put into organizing records today can pay off when it is time to negotiate. Start early, be thorough, and do not hesitate to seek professional guidance if the claim becomes complicated.