Workplace Injury Claim vs Workers Compensation: Key Differences
Understand workplace injury claim versus workers compensation and what is the difference. Call (833)-670-8160 for a free case review.
By Elowyn Parker
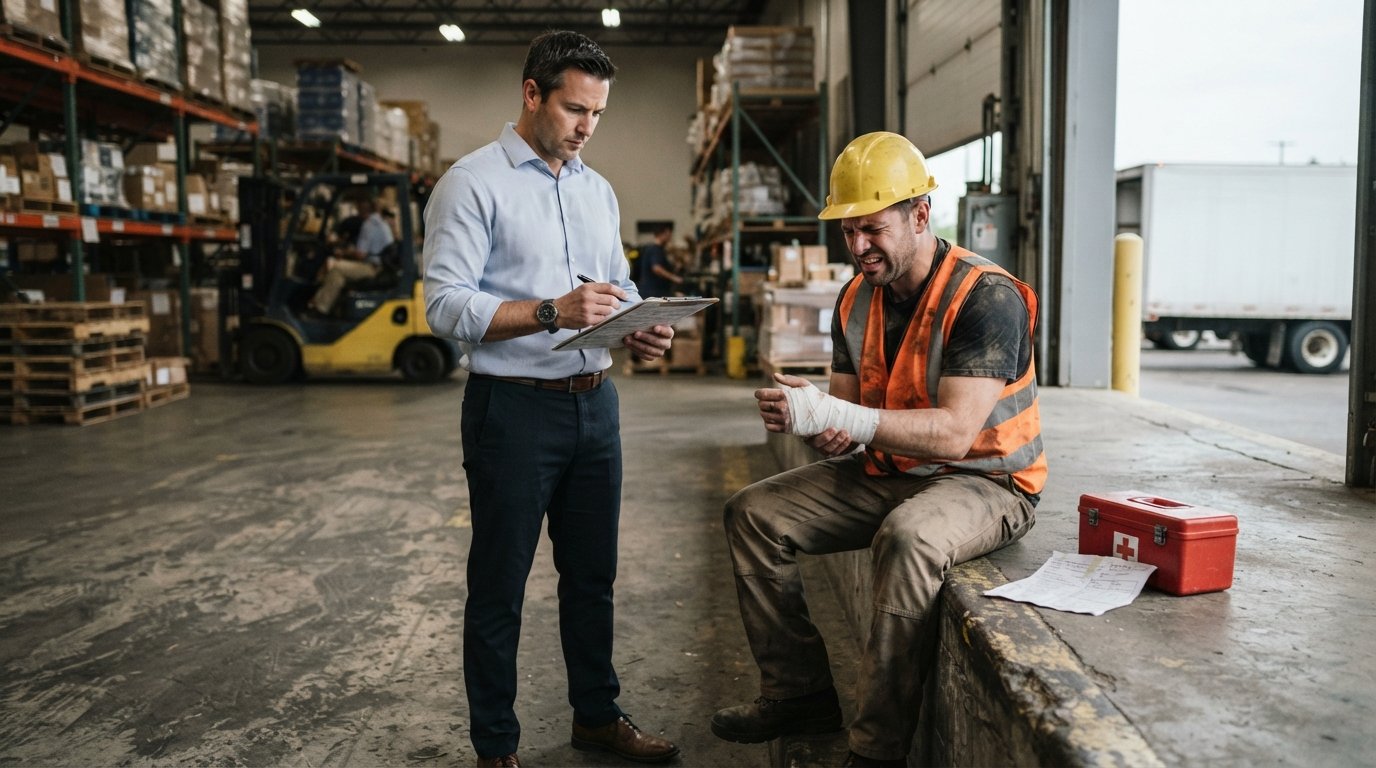
When you are hurt on the job, the first question is often not about how you will pay the bills but about which legal path you are supposed to take. The confusion between a workplace injury claim versus workers compensation is one of the most common sources of missed deadlines and lost benefits. Understanding what is the difference between these two routes is not academic: it decides whether you can recover for pain and suffering, whether you can sue someone other than your employer, and whether your medical care is paid for while you recover.
This guide explains the boundary between the workers compensation system and a personal injury claim arising from the same accident. It covers the exclusive remedy rule, the limited exceptions that allow a third-party lawsuit, how benefits differ, the deadlines that quietly expire, and how a settlement in one claim can affect the other. The goal is practical clarity before you sign anything or speak to an insurance adjuster.
The Core Difference: No-Fault Benefits vs. Fault-Based Recovery
Workers compensation is a no-fault insurance system. You do not need to prove that your employer was negligent to receive benefits. In exchange for giving up the right to sue your employer for negligence, you receive medical coverage and wage replacement benefits regardless of who caused the accident. The system was designed as a bargain: swift, relatively certain benefits in exchange for limited damages.
A workplace injury claim, by contrast, is a fault-based civil action. You must prove that another party owed you a duty of care, breached that duty, and caused your injuries. In return for that higher burden, you can recover damages that workers compensation does not cover, including pain and suffering, emotional distress, and in some cases punitive damages. The practical difference is enormous: comp pays the bills, while a third-party claim can compensate for the human cost of the injury.
Most injured workers do not choose one system over the other. They file a workers compensation claim for medical care and lost wages, and separately pursue a third-party claim against a manufacturer, contractor, or property owner whose negligence contributed to the accident. These two tracks can run in parallel, but they interact in ways that require careful coordination.
The Exclusive Remedy Rule and What Workers Compensation Covers
The exclusive remedy rule is the legal principle that makes workers compensation your only remedy against your employer for a work-related injury. In most states, if your employer carries workers compensation insurance and you are injured in the course and scope of employment, you cannot sue your employer for negligence. The rule is broad, but it has limits. It generally does not protect third parties, and it may not protect an employer in certain intentional misconduct scenarios or where the employer has opted out of the system.
What workers compensation generally covers is narrower than most people expect. The standard benefits include:
- Medical treatment for the work injury, including doctor visits, surgery, prescriptions, and rehabilitation, usually without copays or deductibles.
- Wage replacement, typically around two-thirds of your average weekly wage, subject to state caps.
- Permanent disability benefits if the injury leaves lasting impairment.
- Death benefits for dependents if the injury is fatal.
What workers compensation does not cover is just as important. It generally excludes pain and suffering, emotional distress, loss of enjoyment of life, and punitive damages. It also may not fully replace your lost income, and it may not cover future earning capacity losses if you cannot return to your prior occupation. That gap is precisely why third-party claims matter.
State rules vary significantly. Some states allow employers to opt out of workers compensation, which can open the door to a direct negligence suit. Others have strict rules about which injuries count as work-related, especially for remote workers, traveling employees, and injuries that develop over time. If your situation is unusual, a consultation with a licensed attorney in your state is the only reliable way to know which system applies.
When a Third-Party Claim Exists Alongside a Comp Claim
A third-party claim is a personal injury lawsuit against someone other than your employer. The most common scenarios involve equipment manufacturers, general contractors on multi-employer worksites, property owners, and drivers who cause accidents while you are working. If a defective machine causes your injury, the manufacturer may be liable. If a general contractor fails to maintain a safe site, that contractor may be liable. If you are injured in a car accident while driving for work, the at-fault driver may be liable.
The key distinction is that the third party must owe you a duty of care independent of your employment relationship. Your employer's duty typically arises from the employment relationship and is handled by the exclusive remedy rule. A third party's duty arises from general negligence law. That is why a single accident can generate two separate claims with different defendants, different insurance policies, and different damages.
There is an important limitation: you cannot use a third-party claim to circumvent the exclusive remedy rule and sue your employer in disguise. Courts look at the substance of the relationship, not just labels. If a general contractor is effectively your employer for workers compensation purposes, the exclusive remedy rule may still apply. The analysis is fact-specific, and getting it wrong can forfeit both claims.
Another wrinkle is the lien. If workers compensation pays your medical bills and wage benefits, the comp insurer often has a right to be reimbursed from any third-party recovery. This lien can significantly reduce what you actually keep from a third-party settlement. Experienced attorneys negotiate these liens, sometimes reducing them substantially, but the process requires knowing the state rules and the insurer's practices. If you are handling a claim without representation, you should understand how liens work before you settle. Our guide on negotiating an injury claim without a lawyer explains the risks of going it alone, including the lien problem.
How Benefits Differ: Medical Coverage, Wage Replacement, and Pain and Suffering
The benefit structures of the two systems diverge sharply, and that divergence drives most strategic decisions in these cases. Workers compensation is designed to be comprehensive for medical care but limited for income and nonexistent for general damages. A third-party claim is the reverse: it can capture the full human cost of the injury but requires proof of fault and may take years to resolve.
On medical coverage, workers compensation generally pays for all reasonable and necessary treatment related to the injury, often through a network of approved providers. You may have less choice of doctor than you would with private insurance, and disputes over treatment authorization are common. A third-party claim does not pay medical bills as they arise; instead, it seeks reimbursement for past and future medical expenses as part of a damages award or settlement. That means you need another way to pay for treatment while the claim is pending, which is one reason the two claims often run together.
On wage replacement, workers compensation typically pays a percentage of your average weekly wage, subject to state maximums. The percentage varies by state and by whether the disability is temporary or permanent. A third-party claim can recover the full amount of lost earnings, including overtime, bonuses, and future earning capacity, but only if you can prove them. The difference can be substantial for high earners or workers with long careers ahead of them.
On pain and suffering, the distinction is absolute. Workers compensation does not compensate you for pain, emotional distress, or loss of enjoyment of life. A third-party claim can. That is often the single largest component of a third-party recovery, and it is the reason injured workers pursue these claims even when comp is paying the bills. The trade-off is that pain and suffering damages are subjective, disputed by insurers, and often require expert testimony to prove.
Deadlines for Reporting Injuries and Filing Claims
Missing a deadline is the most common way injured workers lose rights. The rules differ by state and by claim type, but the pattern is consistent: report the injury quickly to your employer, file the workers compensation claim within the state's deadline, and file any third-party lawsuit within the statute of limitations.
For workers compensation, most states require you to report the injury to your employer within a short window, often 30 days or less, and to file a formal claim within a longer window, often one to two years. Some states have shorter deadlines for occupational diseases that develop over time. For a third-party personal injury claim, the statute of limitations is typically two to three years, but it can be shorter for claims against government entities or in certain special situations.
The deadlines are not interchangeable. Filing a workers compensation claim does not toll the statute of limitations for a third-party lawsuit, and vice versa. If you miss the comp deadline, you may lose medical and wage benefits. If you miss the tort deadline, you may lose the right to sue the third party entirely. Because the deadlines vary so much by state and by claim type, the safest approach is to consult a licensed attorney in your state as soon as possible after the injury. If you are unsure whether you need a lawyer, an initial consultation is usually free and does not create an attorney-client relationship.
Documentation matters as much as timing. Report the injury in writing, keep copies of everything, photograph the accident scene and your injuries, and preserve witness contact information. In third-party cases, evidence can disappear quickly, especially on construction sites and in manufacturing settings. The sooner evidence is preserved, the stronger both claims become.
How Settlements in One Claim Affect the Other
Settlements in workers compensation and third-party claims interact in ways that surprise many injured workers. The most important interaction is the comp lien. If you settle a third-party claim, the workers compensation insurer generally has a right to reimbursement for benefits it paid, up to the amount of your recovery. Some states allow the insurer to claim a share of the settlement, while others limit reimbursement to the amount of benefits paid. The rules vary, and the negotiation over the lien can materially change your net recovery.
There is also a credit issue. If you settle a third-party claim, the workers compensation insurer may be entitled to a credit against future benefits, meaning it can reduce or suspend payments until the credit is exhausted. That can matter if you need ongoing medical care or wage benefits after the third-party settlement. The structure of the settlement, including how it allocates damages among medical expenses, lost wages, and pain and suffering, can affect how the credit and lien are applied.
A workers compensation settlement, by contrast, usually resolves the comp claim but does not automatically resolve the third-party claim. However, the release language matters. Some comp settlements include broad releases that could be read to waive other claims, and some require you to disclose any third-party claim. Signing a comp settlement without understanding its effect on a pending third-party claim can be a costly mistake.
Because of these interactions, coordination between the two claims is essential. The timing of settlements, the allocation of damages, and the negotiation of liens all affect the total recovery. Attorneys who handle both types of claims can structure the resolution to maximize the net benefit, while attorneys who handle only one may miss the interaction entirely. If you are considering a settlement in either claim, it is worth having a lawyer review the documents before you sign.
Practical Steps to Protect Your Rights
The practical path forward depends on the facts, but a few steps apply in almost every case. First, report the injury to your employer in writing and keep a copy. Second, seek medical treatment promptly and follow the provider's recommendations, because gaps in treatment are used against injured workers in both systems. Third, preserve evidence, including photographs, witness information, equipment records, and incident reports. Fourth, do not sign anything from an insurer without review, including releases, settlement agreements, and medical authorizations that are broader than necessary.
Fifth, identify all potential defendants early. A workplace accident often involves multiple parties: the employer, a general contractor, a subcontractor, a manufacturer, a property owner, or a driver. Each may have separate insurance and separate liability. Identifying them early preserves options and prevents deadlines from expiring unnoticed. Sixth, understand the lien and credit rules in your state before you settle either claim. The interaction between the two claims is where most of the money is won or lost.
Finally, consider professional guidance. The workers compensation system is administrative and often navigable without a lawyer for straightforward claims, but third-party claims are civil litigation and involve complex proof, expert witnesses, and negotiation with insurers. The stakes are high enough that an initial consultation is almost always worthwhile. If you are an attorney or law firm looking to connect with clients who need this kind of guidance, platforms such as AttorneyLeads provide pre-screened legal leads in practice areas including personal injury and workers compensation, helping firms reach motivated consumers efficiently.
Understanding the difference between a workplace injury claim and workers compensation is ultimately about knowing which system applies to which part of your loss. Workers compensation covers the medical and wage consequences of a work injury without proof of fault. A third-party claim covers the human consequences, but only against someone other than your employer and only with proof of negligence. The two systems are not rivals; they are complements, and the injured workers who do best are the ones who understand how they fit together before the deadlines start running.