Rights of Accident Victims: Insurance Adjuster Tactics
Protect your rights against insurance adjuster tactics. Call 8336708160 for a free case review and avoid a lowball settlement.
By Virelle Dawson
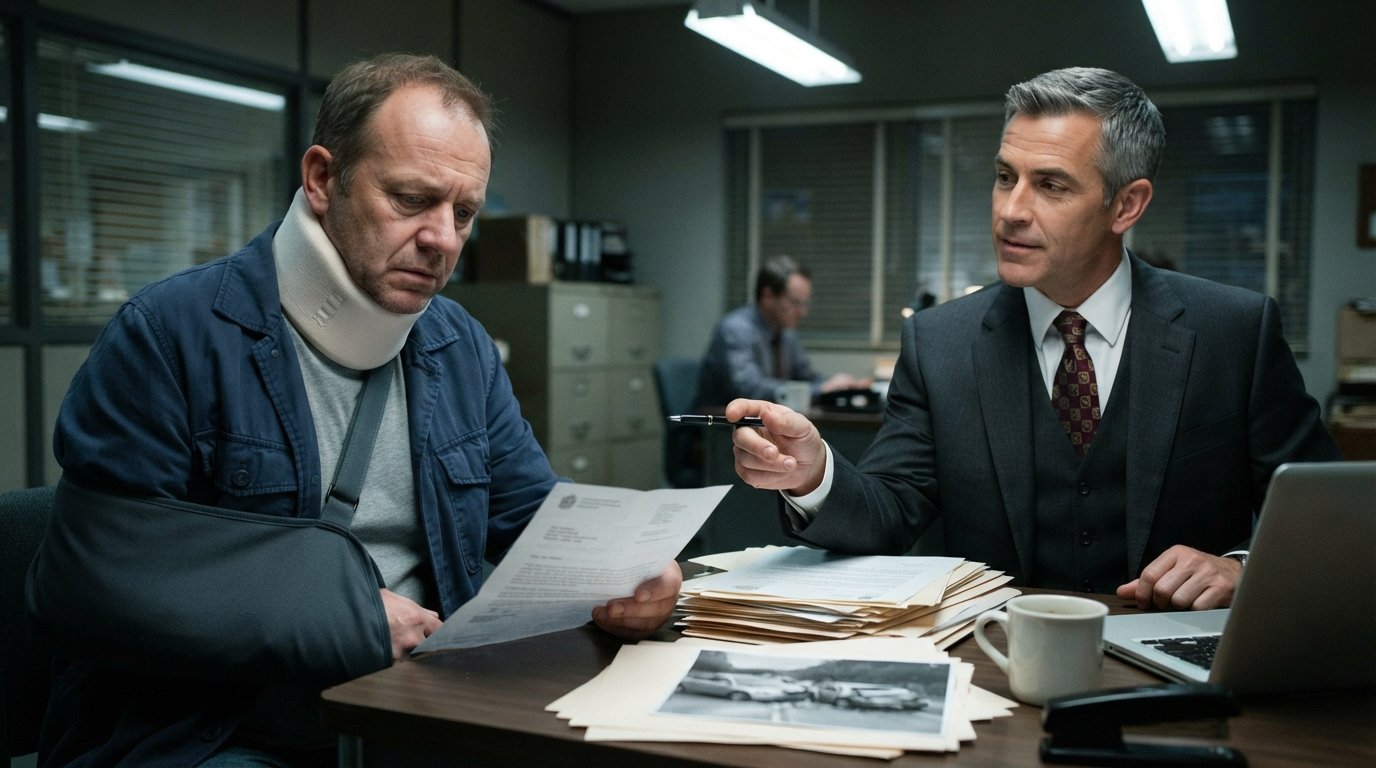
Insurance adjusters are trained negotiators who handle hundreds of claims per year. You are likely dealing with one for the first time. That imbalance is not an accident, it is the business model. Insurers profit when claims close fast and cheap, and adjusters are evaluated on how little they pay. Understanding the rights of accident victims and the insurance adjuster tactics used against them is the first real step toward protecting your recovery. The following guide breaks down the specific methods adjusters rely on, why they work, and how you can push back without damaging your claim.
Your Core Rights After an Accident
Before examining the tactics, it helps to be clear about what you are actually entitled to. These rights do not disappear because an adjuster is friendly on the phone or because you signed a recorded statement you did not fully understand.
As an accident victim, you generally have the right to:
- Receive the full policy limits available under the at-fault driver's coverage, and under your own uninsured or underinsured motorist coverage where applicable.
- Reject a settlement offer that does not cover your past, current, and reasonably anticipated future medical costs.
- Consult an attorney before signing any release, waiver, or recorded statement.
- Recover compensation for lost wages, reduced earning capacity, pain and suffering, and other non-economic damages in many jurisdictions.
- File a bad faith claim or a civil lawsuit if the insurer handles your claim improperly or unreasonably delays payment.
These rights exist whether or not you hire a lawyer. What changes when you hire a lawyer is leverage. Insurers know that an unrepresented claimant is far more likely to accept a low initial offer, and their internal claim-handling guidelines often reflect that reality. If you are still deciding whether representation makes sense, a free case review through a service like LawyerOffer can clarify your options before you speak with the adjuster again.
Adjuster Tactics Designed to Lower Your Payout
Most adjuster tactics are not illegal on their face. They operate in the gray area between aggressive negotiation and bad faith, and that is precisely why they are effective. Recognizing them in real time is the skill that separates claimants who recover fairly from those who settle for a fraction of what their case is worth.
The Immediate Lowball Offer
One of the most common tactics is the early offer. Within days of the accident, sometimes before you have finished treatment, an adjuster calls with a number that sounds generous in the moment. The offer is usually calculated to cover your current medical bills plus a small amount for inconvenience, with nothing for future care, lost income, or pain and suffering.
The trap is timing. You cannot know the full value of your claim until you reach maximum medical improvement, the point where your condition is stable and doctors can predict what ongoing care you will need. Accepting an early offer means signing a release that permanently bars you from seeking more money later, even if complications emerge. Adjusters know this. Their supervisors track how many claims close within the first thirty days, and quick closures are rewarded.
Recorded Statements and Casual Conversations
Adjusters often ask for a recorded statement "just to confirm the details." This sounds procedural. It is actually evidence gathering. During that call, the adjuster will look for inconsistencies in your account, ask about pre-existing conditions, and steer the conversation toward anything that suggests the accident was partly your fault.
You are generally not required to give a recorded statement to the other driver's insurer, and you should be cautious even with your own carrier, which may later use your words to reduce or deny coverage. If you do provide one, prepare in advance, keep answers short and factual, and never speculate about fault or the severity of your injuries.
Delays, Silence, and Endless Requests for Documentation
Another tactic is the slow walk. The adjuster requests medical records, then requests them again from a different provider. They claim the file is under review. They go on vacation without reassigning your claim. Meanwhile, your bills accumulate and your savings drain. The strategy is to make waiting so painful that you accept a low offer just to end the process.
If you suspect that your claim is being stalled on purpose, our article on undervalued medical bills by insurance explains what typically happens next and how to respond when an insurer disputes your treatment costs.
Disputing Causation and Pre-Existing Conditions
Adjusters frequently argue that your injuries were caused by something other than the accident. They pull your medical history looking for prior back pain, old sports injuries, or degenerative conditions, then use those records to argue that the accident only aggravated an existing problem. In some cases, they hire a defense medical examiner who is paid by the insurer and reliably produces a favorable report.
This tactic works because causation is genuinely complicated in personal injury law. The burden is on you to connect your injuries to the accident, and the insurer will exploit any gap in that chain. Consistent medical documentation from the outset is the strongest countermeasure.
Fault-Shifting and Comparative Negligence
Even in clear rear-end collisions, adjusters will probe for evidence that you contributed to the crash. Did you brake suddenly? Were you distracted? Did you fail to wear a seatbelt? In states that follow comparative negligence rules, any percentage of fault assigned to you reduces your recovery proportionally. An adjuster who can pin even twenty percent of the blame on you saves the insurer twenty percent of the payout.
How to Protect Yourself During Negotiations
The best defense against adjuster tactics is preparation. You do not need a law degree to negotiate effectively, but you do need to control the flow of information and avoid the mistakes that permanently weaken your claim.
Start by documenting everything. Keep a file with police reports, witness contact information, photographs of the scene and your injuries, and every medical record related to the accident. Track your mileage to appointments, keep receipts for prescriptions and assistive equipment, and log the days of work you miss. This documentation becomes the backbone of your demand package.
Then follow a disciplined communication strategy:
- Do not give a recorded statement to the other driver's insurer without first understanding your obligations and consulting an attorney if you are unsure.
- Do not sign any release, waiver, or settlement agreement until you have finished treatment or reached maximum medical improvement.
- Do not accept the first offer, and do not negotiate against yourself by naming a number before the adjuster does.
- Put everything important in writing, and keep copies of every letter and email exchanged with the insurer.
- Document every adjuster interaction, including dates, times, names, and what was said.
This approach serves two purposes. It strengthens your negotiating position, and it creates a record you can use if the insurer later acts in bad faith. Many states allow policyholders to recover extra damages when an insurer unreasonably denies or delays a valid claim, but those claims depend on evidence.
When Adjuster Tactics Cross Into Bad Faith
Not every aggressive negotiation tactic is bad faith. Insurers are allowed to dispute damages, question causation, and make low offers. Bad faith generally involves conduct that is unreasonable, deceptive, or in violation of the insurer's duty to act in good faith toward its policyholder. Examples include outright misrepresenting policy limits, failing to investigate a claim promptly, denying coverage without a reasonable basis, or offering far less than what the evidence clearly supports.
If you believe an insurer has crossed that line, you may have grounds for a bad faith claim in addition to your underlying personal injury claim. These cases often require an attorney because insurers defend them aggressively, and the evidence is usually buried in the claim file, which you may need formal discovery to access.
It is also worth noting that the adjuster is not the final decision-maker. Adjusters operate within authority limits set by supervisors, and larger settlements require approval from higher levels. Sometimes the person on the phone genuinely cannot offer more. Knowing when you are dealing with a tactical lowball and when you are dealing with a real authority limit will help you decide whether to keep negotiating or escalate.
Bringing in Legal Help Without Losing Control
Hiring an attorney does not mean giving up control of your case. It means shifting the negotiation burden to someone who handles these tactics daily and who can pursue litigation if the insurer refuses to be reasonable. Most personal injury attorneys work on contingency, meaning you pay nothing upfront and the fee comes out of the recovery only if the case succeeds.
If you are not ready to hire a lawyer, you can still benefit from an early case evaluation. AttorneyLawsuit.com connects accident victims with participating attorneys for a free, confidential, no-obligation review. The site is not a law firm and does not provide legal advice, but it can help you understand whether your claim is strong enough to justify representation and what a reasonable settlement range might look like.
Whatever path you choose, remember that the adjuster's job is to protect the insurer's bottom line. Your job is to protect your rights, your health, and your financial future. Those two goals are not aligned, and the sooner you recognize that, the better positioned you will be to negotiate from strength rather than desperation.