Gray Divorce Trends and Legal Considerations After 50
Gray divorce trends and legal considerations after 50 explained. Call 8336708160 for a free case review and protect your retirement.
By Bryn Holloway
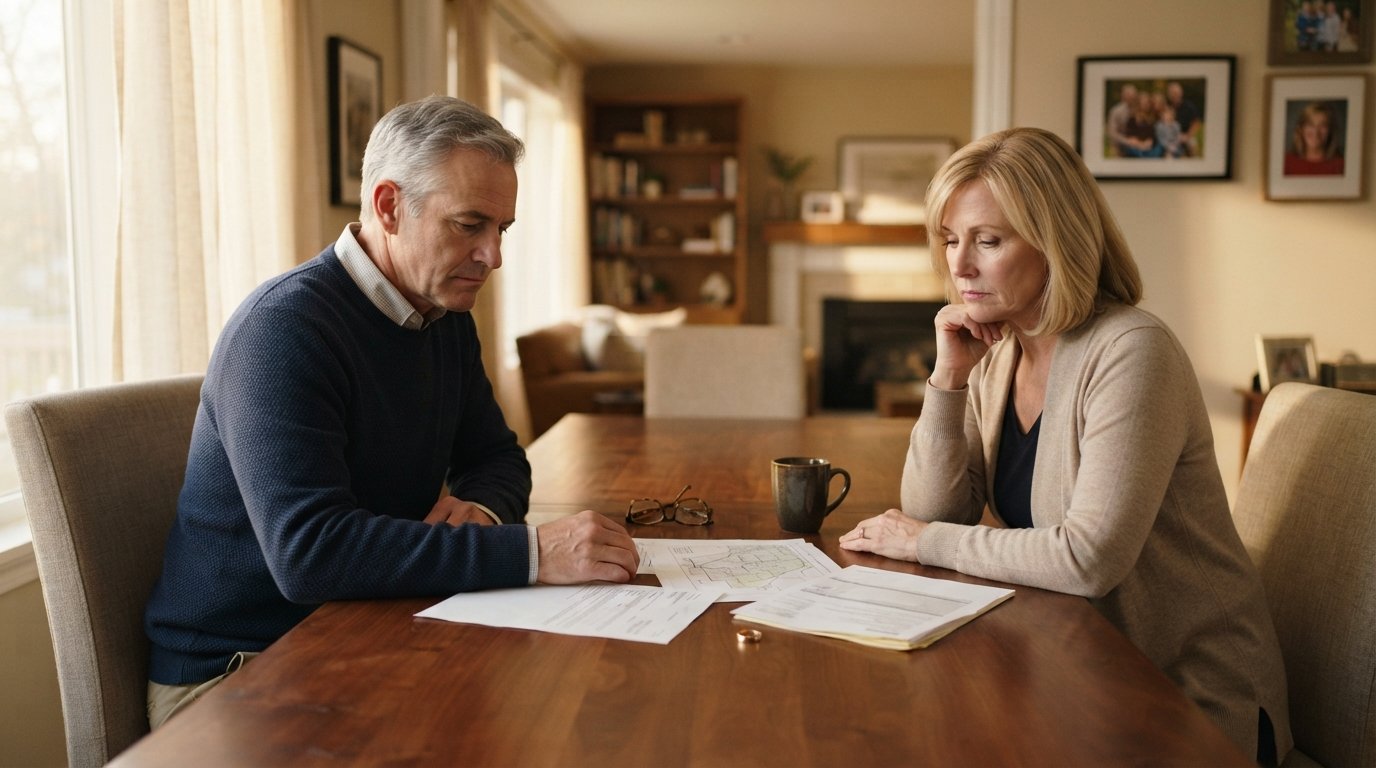
Divorce after age 50, often called gray divorce, has reshaped how Americans think about late-life separation. What was once a rare event among couples married for decades has become a defining feature of modern family law. According to widely cited research from the National Center for Family and Marriage Research, the divorce rate among adults 50 and older has roughly doubled since 1990, even as the overall divorce rate in the United States has declined. For couples who spent 25, 30, or 40 years building a life together, the decision to part ways raises questions that younger divorcing couples rarely face: how to divide a pension, whether retirement savings will stretch across two households, who keeps the family home, and how to protect adult children from financial and emotional fallout.
Understanding gray divorce trends and legal considerations after 50 is not just an academic exercise. The stakes are different at this stage because there is less time to recover financially, more complex assets to untangle, and often a fixed income on the horizon. Whether you are considering divorce, responding to a filing, or simply researching your options, this guide walks through the major trends, the legal issues that matter most, and the practical steps that can protect your future.
Why Gray Divorce Keeps Rising
The rise in late-life divorce reflects broad social and economic shifts. Longer life expectancies mean couples who marry in their twenties may face 50 or more years together, and many decide they do not want to spend the final third of life in an unhappy marriage. Women's increased workforce participation and earning power have made financial independence more attainable, reducing the economic pressure that once kept unhappy couples together. Cultural stigma around divorce has faded, and adult children, now grown and often living independently, are less likely to be a reason to stay married.
There is also a demographic pattern worth noting. The divorce rate for couples in their fifties and sixties is higher than for any other age group over 40, and a significant share of these divorces involve marriages of 30 years or longer. Researchers have found that about one in four divorces now involves someone over age 50, compared with roughly one in ten in 1990. These are not fleeting marriages; they are long-term partnerships ending late in life, which makes the legal and financial planning far more consequential.
The Financial Realities That Set Gray Divorce Apart
When a couple divorces at 35, both spouses typically have decades of earning years ahead to rebuild. At 55 or 65, that runway is much shorter. Retirement accounts, pensions, Social Security benefits, and the marital home often represent the bulk of the estate, and dividing them can leave both spouses financially strained. A single household cannot usually maintain the same standard of living as the married household did, especially if the couple was living on one primary income.
Health care costs add another layer. Older adults often have higher medical expenses, and losing a spouse's employer-sponsored health insurance before Medicare eligibility at 65 can be a serious financial shock. Long-term care planning, life insurance, and estate documents may all need revision after a gray divorce. These realities mean that a late-life divorce is less about starting over and more about carefully restructuring what already exists.
Key Legal Considerations After 50
Every divorce involves legal issues, but the following areas demand particular attention when one or both spouses are over 50. A qualified family law attorney can help you evaluate how these apply to your specific situation, and resources such as LawyerCaseReview can help you understand how case evaluations and attorney connections work before you commit to representation.
Pensions, 401(k)s, and Retirement Accounts
Retirement assets are frequently the largest marital asset in a gray divorce, and dividing them incorrectly can trigger taxes, penalties, or a reduced retirement income. Employer pensions and 401(k) plans generally require a Qualified Domestic Relations Order (QDRO) to divide benefits without immediate tax consequences. IRAs are typically divided through a transfer incident to divorce. The details matter: whether benefits are defined benefit or defined contribution, whether the pension includes survivor benefits, and whether the account holds pre-tax or Roth funds all affect the outcome. Courts may also consider the earning capacity of each spouse and the length of the marriage when allocating retirement assets.
Social Security and Spousal Benefits
Social Security rules are frequently misunderstood in gray divorce. If you were married for at least 10 years, you may be eligible to claim benefits based on your ex-spouse's work record, even after divorce, provided you are unmarried at the time you claim and both parties are at least 62. Claiming on an ex-spouse's record does not reduce the ex-spouse's benefit. For many older divorcing adults, this can be a meaningful source of income, but timing and eligibility rules are strict, so professional guidance is essential.
The Marital Home and Real Estate
The family home often carries emotional weight, but keeping it can be financially risky after 50. Property taxes, maintenance, insurance, and mortgage payments may be difficult to sustain on a single income. Some couples agree to sell the home and split the proceeds; others arrange a buyout, where one spouse refinances and pays the other for their share. A third option, deferred sale, allows one spouse to remain in the home for a set period before it is sold. Each option has tax and cash-flow implications that should be modeled before deciding.
Spousal Support and Alimony
Long marriages often lead to long-term spousal support, especially when one spouse reduced career opportunities to raise children or support the other's career. Courts consider the length of the marriage, the standard of living during the marriage, each spouse's earning capacity, and the age and health of both parties. In many states, marriages of 20 years or more may result in indefinite or long-term alimony, though the trend in recent years has favored more predictable formulas and defined durations. Tax treatment of alimony changed after 2018, so both payers and recipients should understand how the current rules affect their bottom line.
Estate Planning and Beneficiary Designations
Divorce does not automatically update every document. Wills, trusts, powers of attorney, health care directives, and beneficiary designations on life insurance and retirement accounts may still name a former spouse unless they are changed. In a gray divorce, estate planning is not optional; it is a core part of protecting your wishes and your heirs. A family law attorney and an estate planning attorney often work together to align the divorce settlement with a new estate plan.
Health Insurance and Medicare Transitions
Losing coverage through a spouse's employer plan is one of the most immediate practical problems in a gray divorce. If you are under 65, you may need to enroll in a marketplace plan, COBRA, or a plan through your own employer. If you are 65 or older, you may already be on Medicare, but supplemental coverage and prescription drug plans may need to be revisited. The divorce settlement can address who pays for health insurance premiums during a transition period, and a court may order one spouse to maintain coverage for the other for a defined time.
Gray Divorce Trends and Legal Considerations After 50: Practical Steps
Preparation is the best defense against the uncertainty of a late-life divorce. The following steps can help you organize your finances, clarify your goals, and reduce the risk of costly surprises.
- Gather your financial documents. Collect statements for retirement accounts, pensions, bank accounts, investments, mortgages, and debts. A complete financial picture is the foundation of any settlement negotiation.
- Understand your state's divorce laws. Whether you live in a community property state or an equitable distribution state affects how assets are divided. State rules on alimony, property division, and retirement benefits vary widely.
- Consult a family law attorney early. An attorney can explain your rights, identify risks, and help you avoid mistakes that are difficult to reverse. Many offer initial consultations, and services like AttorneyLawsuit.com connect consumers with attorneys for free case reviews.
- Consider mediation or collaborative divorce. These processes can be faster, less expensive, and less adversarial than litigation, which matters when both spouses want to preserve assets for retirement.
- Update your estate plan and beneficiary designations. After the divorce is final, revise your will, trusts, powers of attorney, and account beneficiaries to reflect your new circumstances.
Each of these steps builds on the last. Skipping the financial inventory, for example, can lead to an unfair settlement, while ignoring estate planning can undo the protections you negotiated. The goal is not to win a contest but to emerge with a workable plan for the next 20 or 30 years.
Special Issues Involving Adult Children and Grandchildren
Gray divorce does not end parenting, even when children are grown. Adult children may feel caught between parents, and grandchildren can become pawns in family conflict if the divorce is acrimonious. From a legal standpoint, adult children generally have no custody or support rights, but they may be beneficiaries of family trusts, life insurance policies, or estate plans that need updating. Some couples choose to address college support, wedding expenses, or inheritance expectations in the settlement to reduce future disputes.
Emotionally, the impact on adult children is real. Many report feeling a renewed sense of loss, even decades after leaving home. Family therapists and divorce coaches often recommend clear communication, avoiding the temptation to recruit children as allies, and setting boundaries around holidays and family events. These steps do not resolve legal issues, but they can preserve relationships that matter long after the divorce is final.
Common Mistakes to Avoid
Gray divorce cases often go wrong in predictable ways. One frequent error is trading retirement assets for the house without modeling the long-term financial consequences. Another is failing to obtain a QDRO, which can delay or reduce retirement benefits. Some spouses waive spousal support without understanding how it interacts with Social Security or pension survivor benefits. Others neglect to update beneficiary designations, leaving an ex-spouse as the recipient of a life insurance payout or retirement account.
Another mistake is assuming that a long marriage guarantees a particular outcome. Family law varies by state, and judges have discretion. A settlement that seems fair on paper may be unworkable in practice if it leaves one spouse without affordable health insurance or adequate housing. Working with an experienced attorney and, where appropriate, a financial advisor can help you test assumptions before you sign.
How an Attorney Can Help
An experienced family law attorney does more than file paperwork. They evaluate the marital estate, identify hidden or undervalued assets, negotiate with opposing counsel, and present your case to a judge if settlement talks fail. They also coordinate with financial professionals, appraisers, and estate planners to ensure that the divorce decree aligns with your broader goals. For anyone over 50, this coordination is especially important because the decisions made today will shape retirement for decades.
If you are researching gray divorce trends and legal considerations after 50, the next step is to speak with a qualified attorney who understands late-life divorce. Many legal professionals offer free, confidential case evaluations, and platforms such as AttorneyLawsuit.com can connect you with attorneys in your area. The information here is educational and is not legal advice; only a licensed attorney can advise you on your specific circumstances.
Gray divorce is not a failure; it is a transition. With careful planning, the right legal guidance, and a clear-eyed view of your finances, you can protect your retirement, your relationships, and your peace of mind as you move into the next chapter.